Borrowing in Morocco
Moroccan banks may lend in dirhams to non-resident foreigners and MREs up to 80% of the property price. The rest is paid in foreign currency, and so are the repayments.
A non-resident foreigner signs a sworn statement that they do not already own a home in Morocco; the loan is paid into a special account. MREs are exempt from this and, since 2026, may finance several properties this way.
Interest rates
According to Bank Al-Maghrib, the average mortgage rate was 4.99% in the third quarter of 2026, across all borrowers. The policy rate has been 2.25% since June 2025. Compare with an offer from a bank in your own country, which may finance the purchase against your assets there.
Read the full guide
Enter your details to read the rest of this guide, and of the five others. A consultant can also answer your questions on WhatsApp.
Tax on rental income
Rent from a property in Morocco is taxed in Morocco. 40% of the gross rent is deducted, and the rest follows the income tax scale:
- up to 40,000 DH: 0%;
- 40,001 to 60,000 DH: 10%;
- 60,001 to 80,000 DH: 20%;
- 80,001 to 100,000 DH: 30%;
- 100,001 to 180,000 DH: 34%;
- above 180,000 DH: 37%.
An example from the tax administration
160,000 DH of gross rent gives 96,000 DH of net income and 10,800 DH of tax, before family allowances. The return is due before 1 March.
Capital gains on resale
Capital gains are taxed at 20%, with a minimum of 3% of the sale price, even with no gain. The purchase price is indexed and increased by acquisition costs (a flat 15%, or the actual amount), works and loan interest.
A main residence occupied for at least five years is exempt, including the home that MREs keep for their stays in Morocco. The return and payment are due within 30 days of the sale.
And at home? The example of France
Under the tax treaty of 29 May 1970, rent from a property in Morocco is taxable only in Morocco. France does not tax it, but takes it into account to set the rate on your other income. Capital gains are taxable in Morocco; how France treats them should be checked with a tax adviser.
For Belgium, the Netherlands, Norway, Spain, Italy or the United Kingdom, the treaty signed with Morocco decides: have it checked before you buy.
Short-term letting
Renting by the night falls under Law 80-14 on tourist accommodation and its 2023 decree: a declaration then an operating licence, ID checks on guests, an individual guest form kept for one year and online declaration of nights. Look into it before letting your villa.
At CITYSTAR
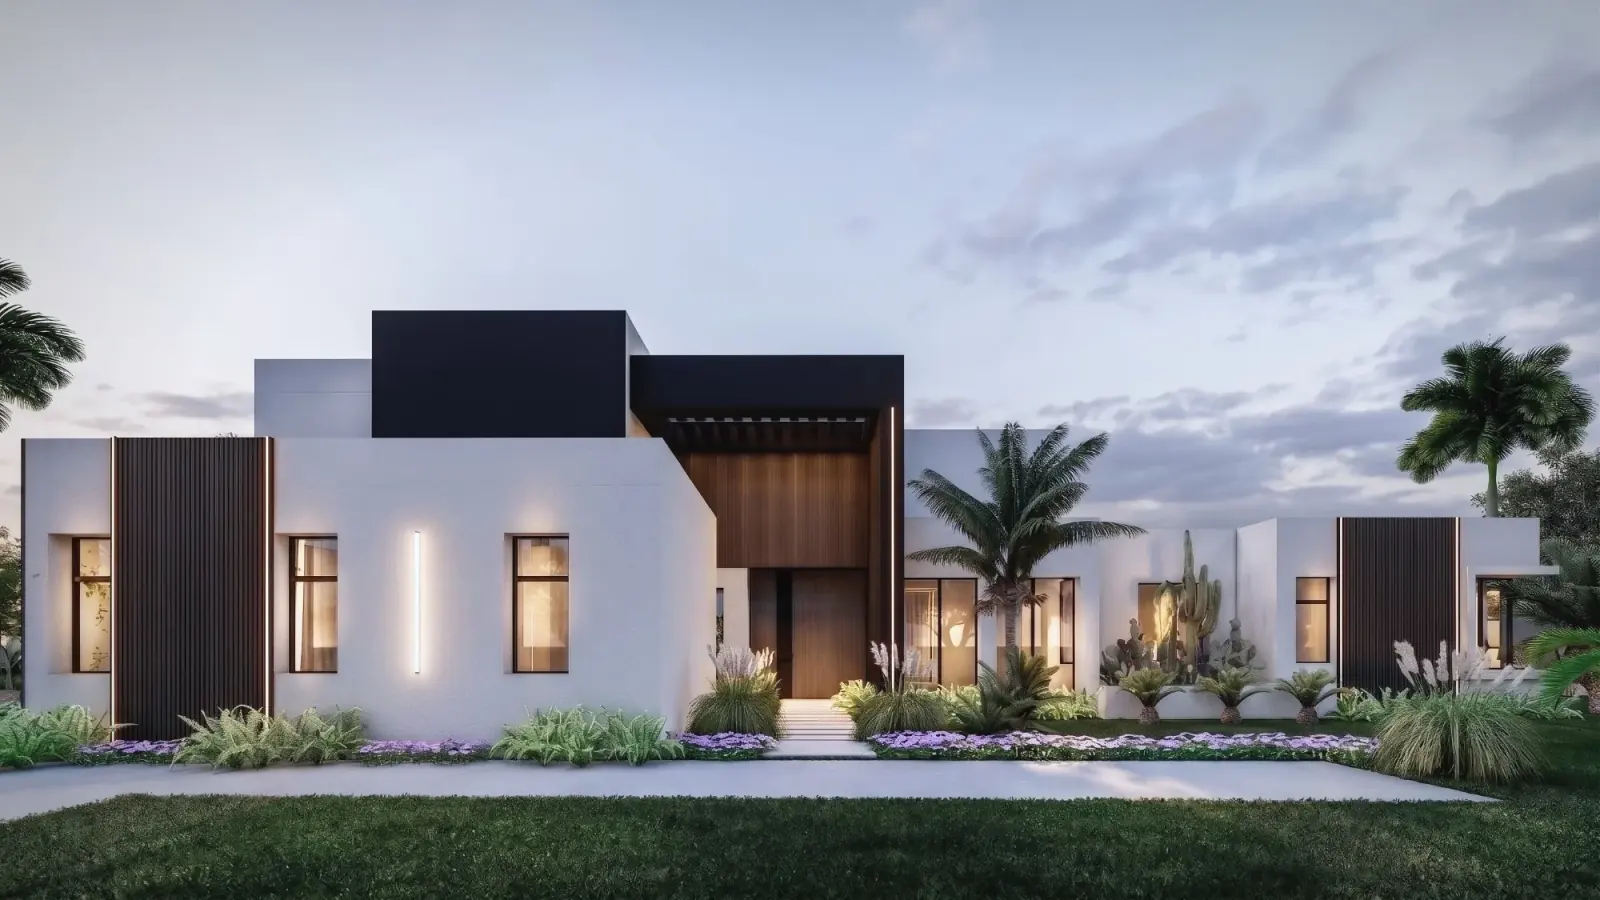
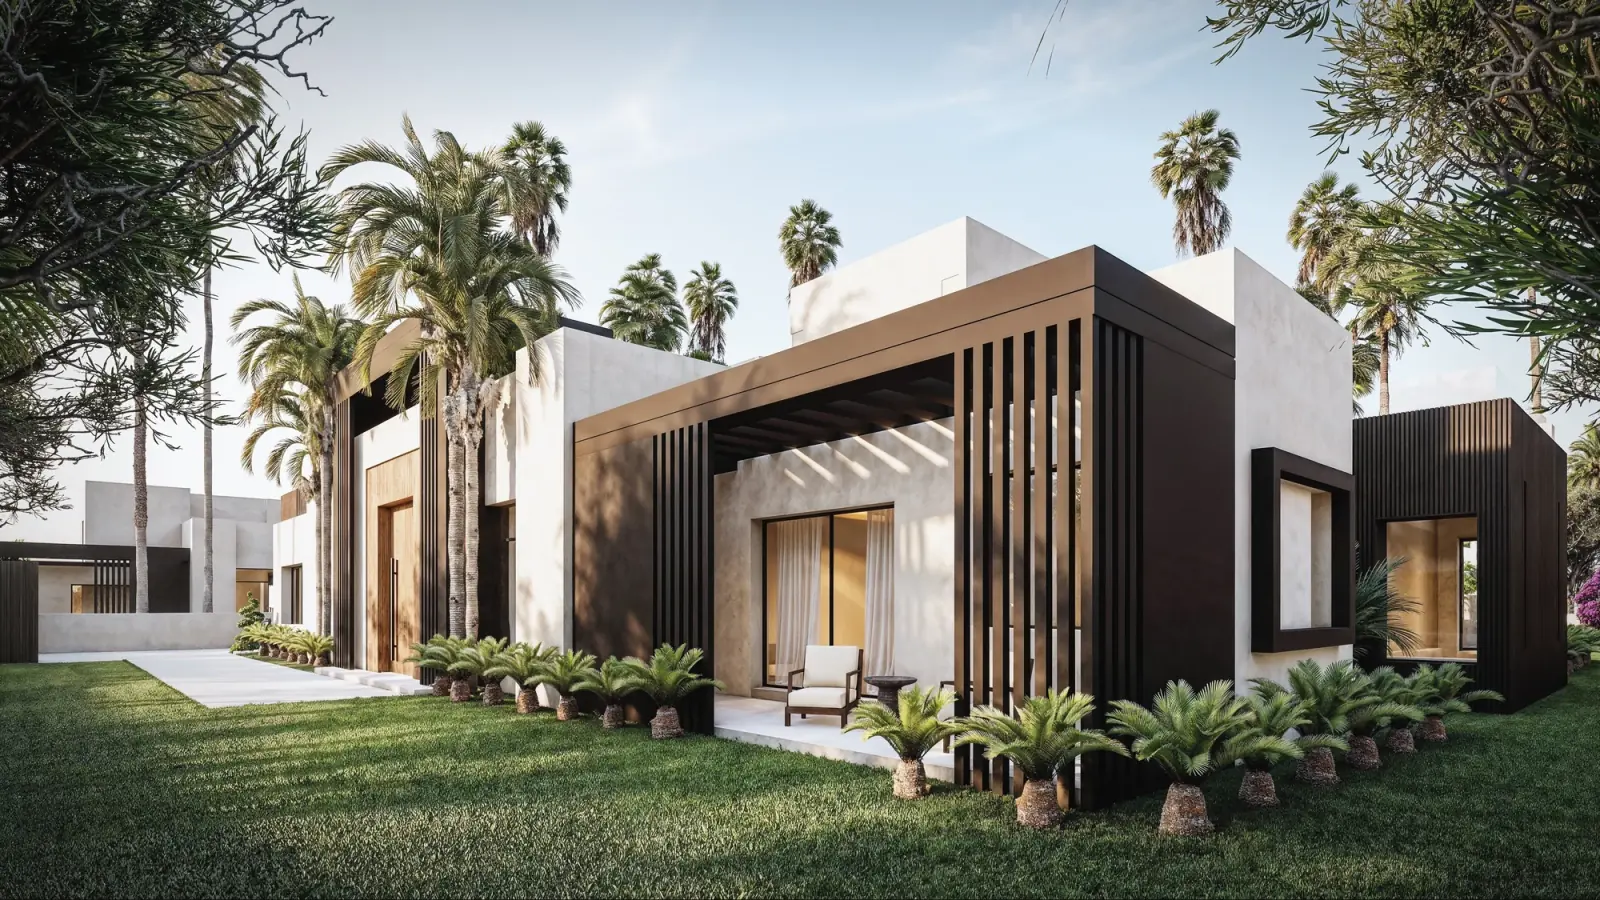
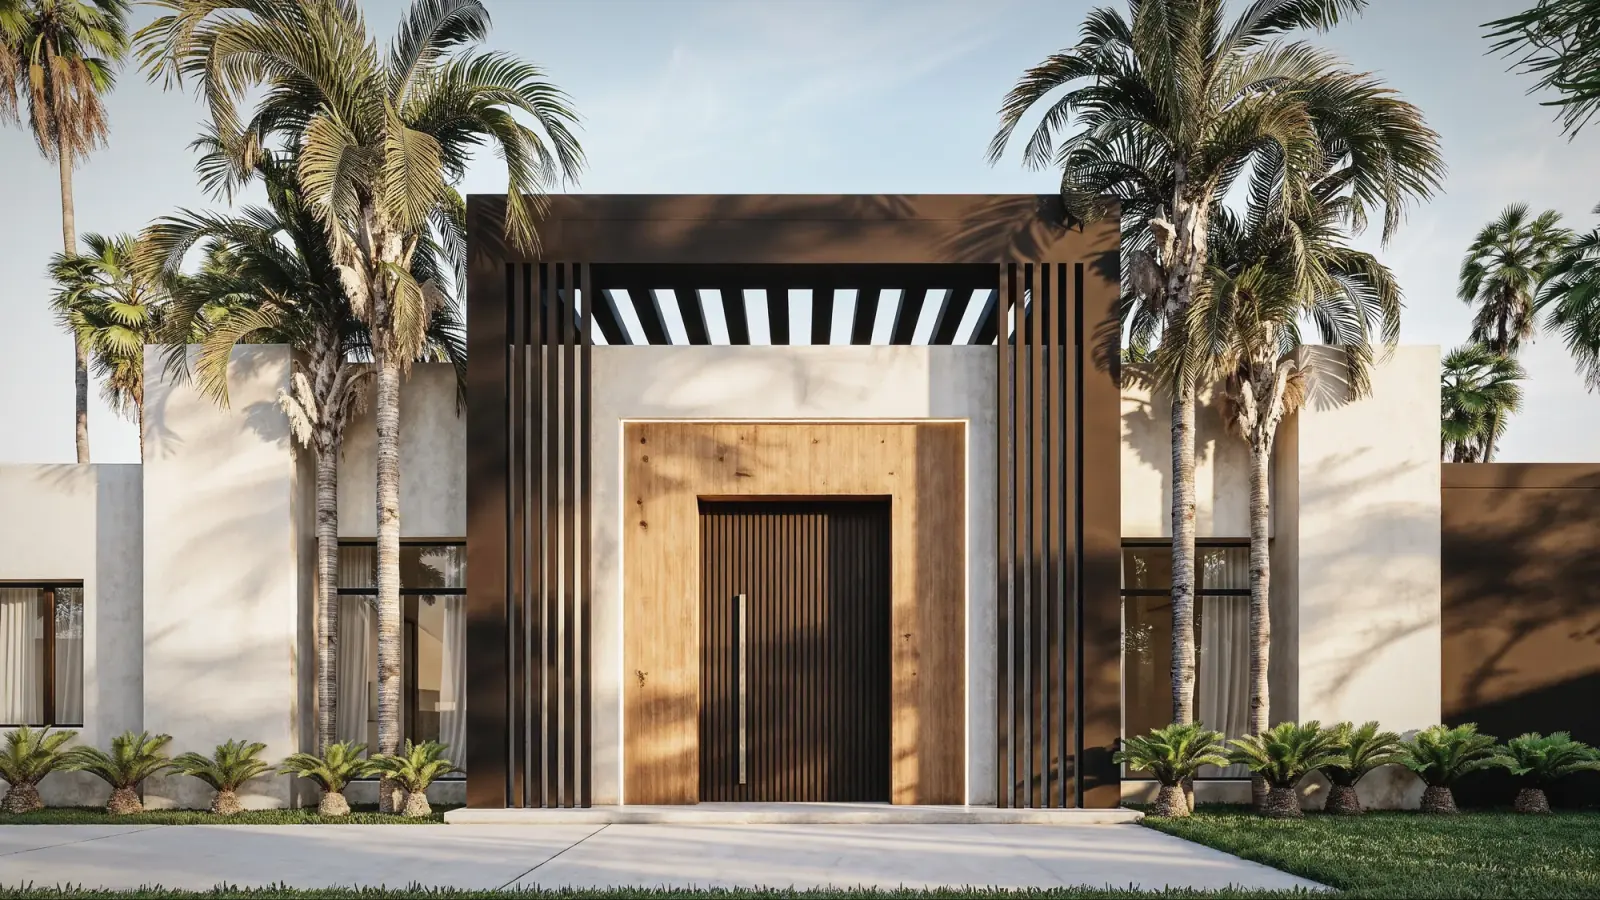
The CITYSTAR estate is fully funded by the developer’s own capital, and you can finance your villa with a bank mortgage. The simulator on the Investing page gives an order of magnitude for rental income, based on illustrative assumptions.
This guide gives general information, up to date at the date shown. It does not replace advice from a notary, a lawyer or a tax adviser, who will take your own situation into account.
Sources
- Office des changes — Instruction générale des opérations de change 2026
- Direction générale des impôts — Code général des impôts 2026
- Direction générale des impôts — Note circulaire n° 737 (loi de finances 2026)
- Bank Al-Maghrib — Taux débiteurs, 3e trimestre 2026
- TelQuel — Bank Al-Maghrib maintient son taux directeur à 2,25 % (22/09/2026)
- Convention fiscale France–Maroc du 29 mai 1970
- BOFiP — Commentaire de la convention fiscale France–Maroc
- Médias24 — Le décret de 2023 sur les hébergements touristiques